January is the best month to renegotiate pallet supply
In short
Recycled pallet supply is a by-product of somebody else finishing with a pallet, so it peaks in January when holiday inventory unwinds and demand has collapsed. That combination — abundant cores, soft order books — is the only point in the year when a buyer negotiates from strength. Agreements signed in January or February consistently price better than the same agreement signed in October.
Talk to us about this
If this piece describes a problem you actually have, describe it back to us in the message field. You will get a written answer from a person within one business day.
Why January specifically
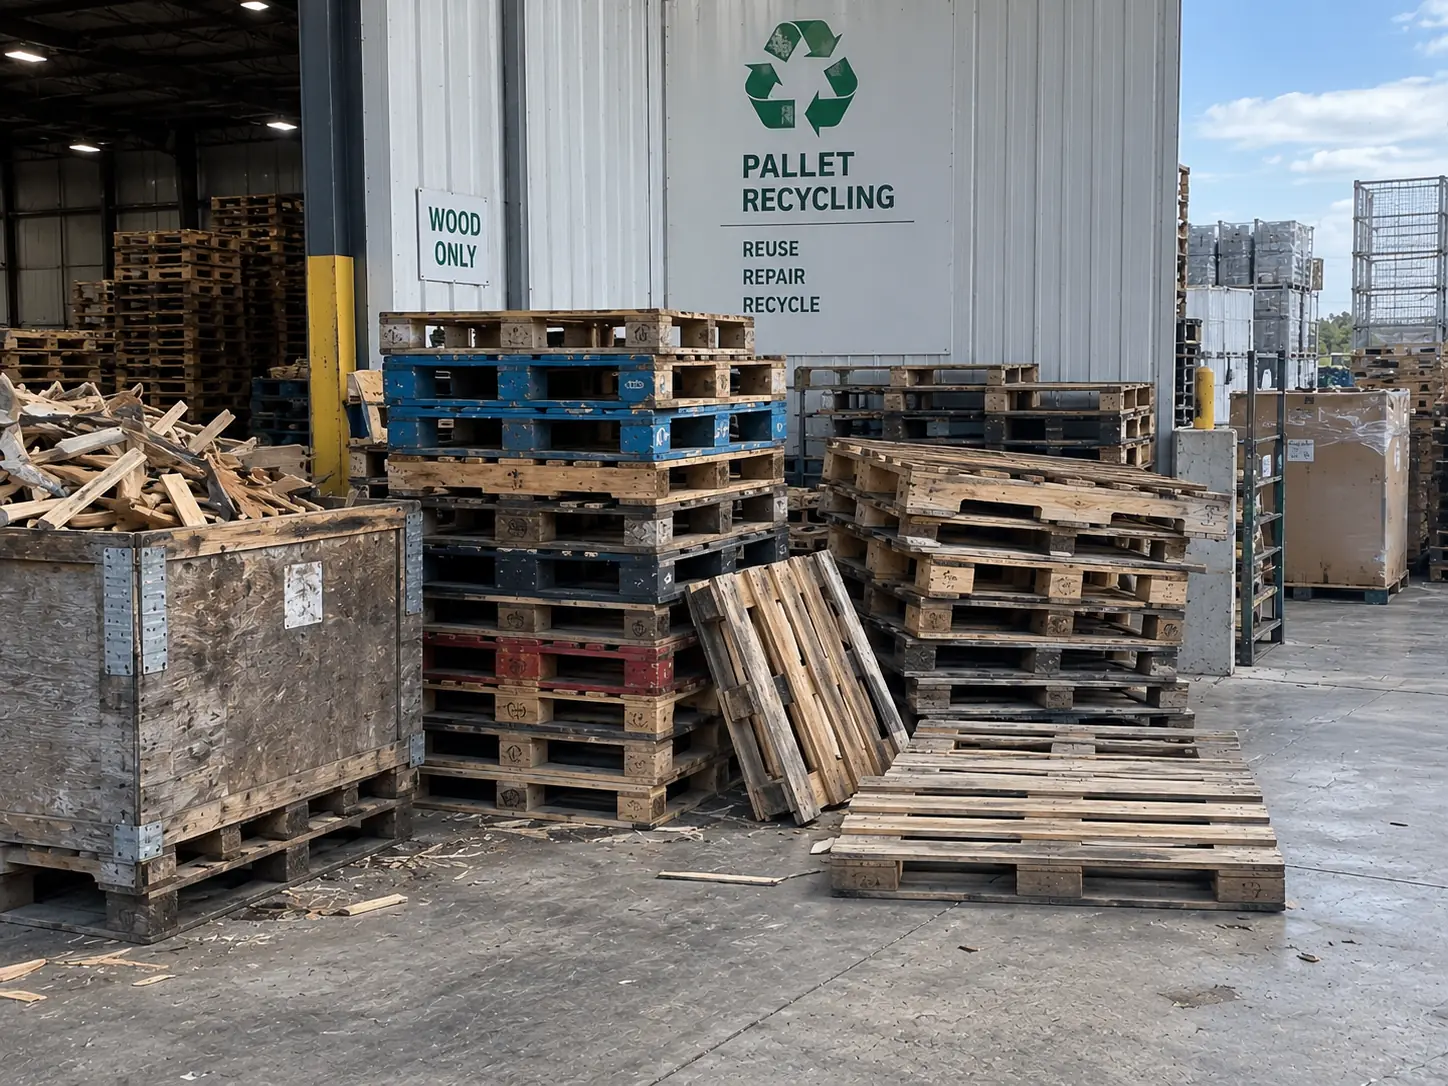
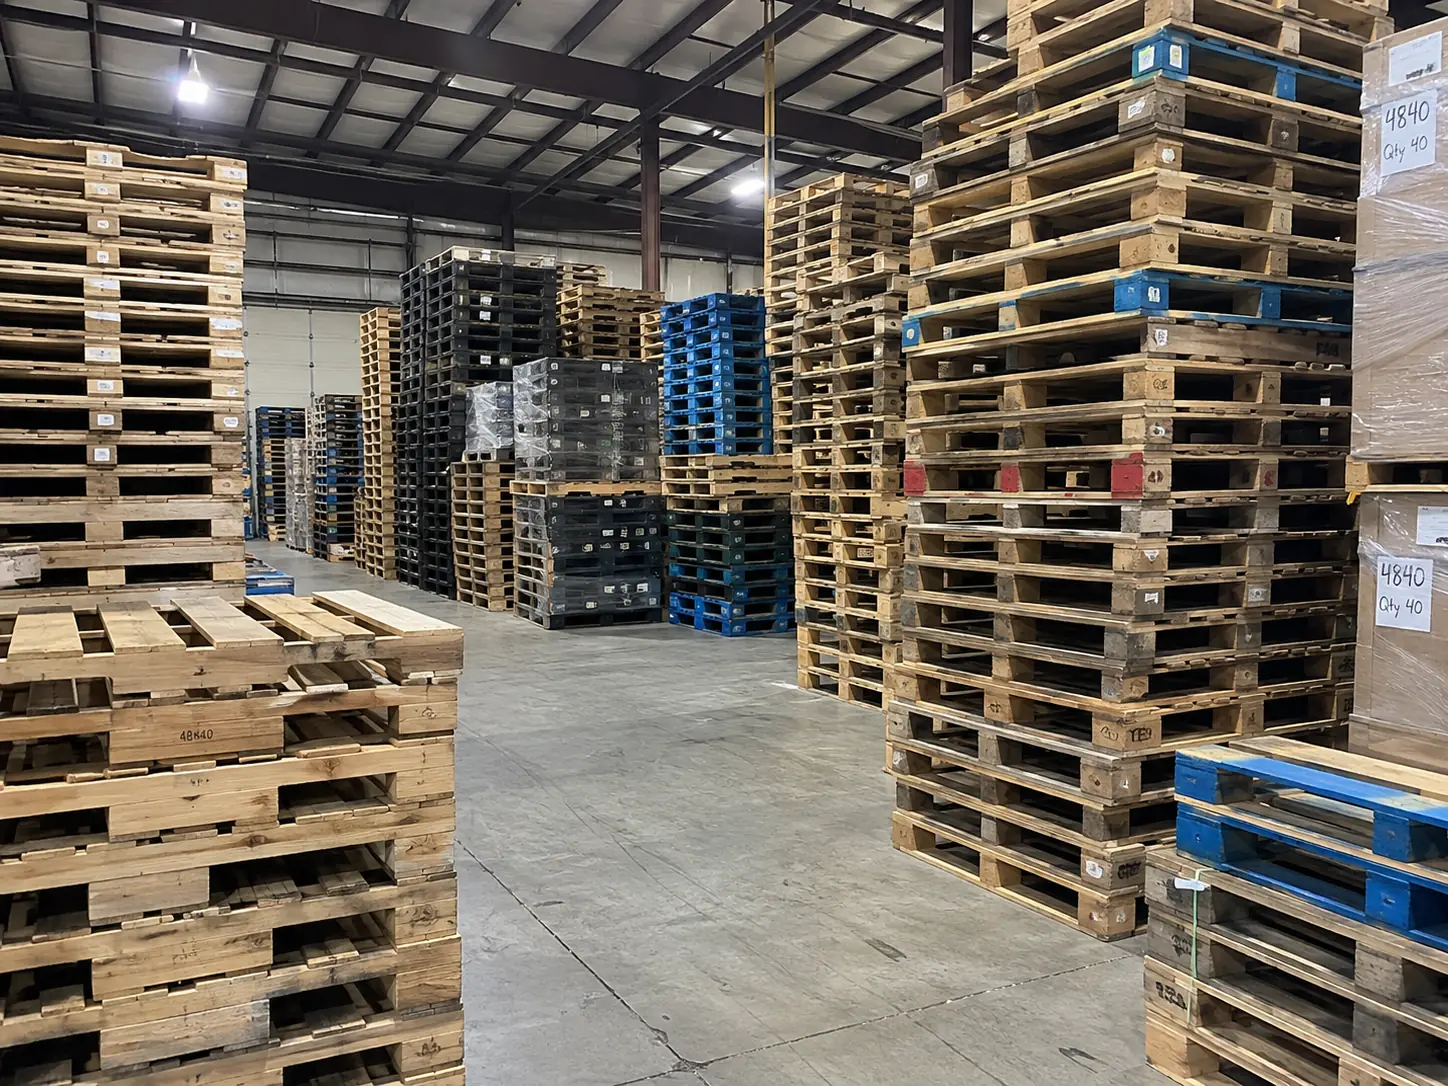
Through November and December, retail and distribution unwind the inventory they spent the autumn building. Every pallet that was sitting under product in a rack becomes an empty pallet on a dock. Simultaneously, order books for the next quarter are soft — nobody is building stock in January. The market flips from scarcity to abundance inside about three weeks.
Yet most supply agreements come up for renewal in the autumn, because that is when procurement calendars happen to land and when somebody notices that prices have gone up. Negotiating scarce supply during a demand peak is not a negotiation; it is an acceptance.
Fix volume, not price
The instinct in a buyer-favourable market is to lock a low unit price for twelve months. On a genuinely seasonal commodity that is a mistake in both directions: a supplier who has committed below cost for Q4 will find ways to prioritise other accounts, and a buyer who has committed above the January market will resent it for nine months.
- Commit volume and cadence — that is what actually lets a supplier plan and price properly
- Agree a mechanism for seasonal movement rather than pretending it will not happen
- Fix the things that genuinely should not move: grade definitions, rejection criteria, lead times, freight terms
- Agree allocation priority in advance, which is worth more than a small discount when the market tightens
- Put the round-trip arrangement in writing if you generate cores — it is the biggest lever in the agreement
What to bring to the conversation
- A grade-by-application map
Which pallets go in racks, which leave the building, which never leave. This is where the money is, and a supplier who sees it can price sharper because they are not pricing in uncertainty.
- Twelve months of actual volume
Not a forecast, the history. Monthly, by grade if you have it. Suppliers price risk, and a documented history removes risk.
- Your core generation
How many empties accumulate, where, and how quickly. If it can be paired with delivery, the unit price conversation changes entirely.
- Your dock constraints
Apron depth, equipment, receiving hours. Nothing raises a delivered price faster than a supplier discovering these at the gate.
- A number you can actually commit to
A commitment you will not honour is worse than no commitment, because it poisons the next negotiation too.
Appendix: the data behind this
Every piece on this site closes with the slice of our operating record that bears on what it argues. The full record is published at /resources/operating-record.
Core supply against demand, indexed
January: supply at 127, demand at 78. October: supply at 86, demand at 121. That inversion is the entire negotiating case.
Read this chart as a table
| Month | Core supply | Demand |
|---|---|---|
| Sep | 92 | 114 |
| Oct | 86 | 121 |
| Nov | 81 | 118 |
| Dec | 89 | 96 |
| Jan | 127 | 78 |
| Feb | 121 | 82 |
| Mar | 112 | 91 |
| Apr | 106 | 97 |
| May | 103 | 101 |
| Jun | 98 | 106 |
| Jul | 94 | 109 |
| Aug | 91 | 112 |